YEL obligation

You need YEL insurance if you work as a self-employed person. Take out YEL insurance from the date you start working and fulfil the insurance conditions.

When do you need YEL insurance?

You must take out YEL insurance if all the following conditions are met:

  • you are at least 18 years old
  • you work in your own business or as a light entrepreneur
  • your self-employment continues for at least four months
  • your YEL income, that is, the value of your work input, is at least EUR 9,423.09 per year (2026).

What are the age limits for YEL insurance?

The minimum age for YEL insurance is 18. Insurance coverage begins at the start of the calendar month following your 18th birthday.

The upper age limit depends on your year of birth:

  • 70 years for those born in 1962 or later
  • 69 years for those born between 1958 and 1961
  • 68 years for those born in 1957 or earlier.

From what date must I take out YEL insurance?

Take out YEL insurance from the date on which your work actually begins (for example, on your first day of work, when your first invoiced work begins, or when you start your self-employed activity).

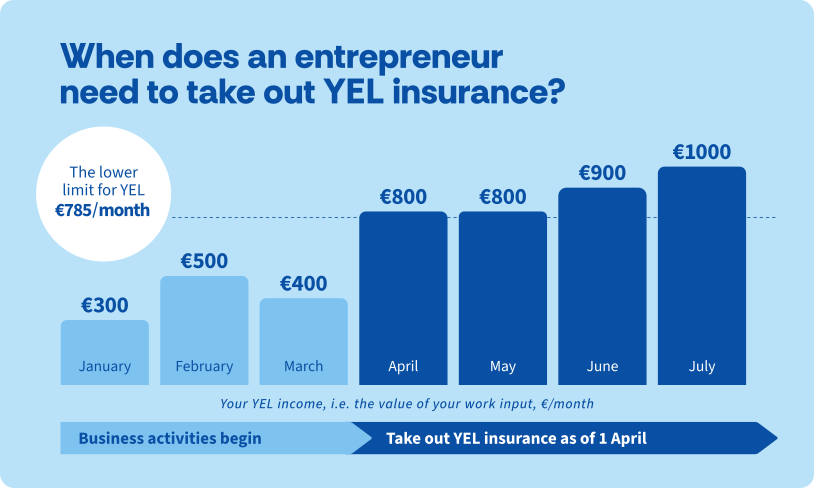
Your entrepreneurial activity must also be extensive enough for your YEL income to be at least EUR 785 per month, or EUR 9,423.09 per year (2026).

The start date of your insurance may differ from your company's registration date if you do not begin working immediately when the business is registered.

You have six months to take out the insurance. However, the start date of your YEL insurance will always be the date on which your entrepreneurial activities began at a level that meets the YEL insurance obligation.

A bar chart showing a self-employed person’s YEL income, i.e. the value of their work input, on a monthly basis. You must take out YEL insurance when your YEL income exceeds the YEL lower limit of EUR 785 per month. In the example, the monthly YEL income rises to EUR 800 in April, at which point YEL insurance is taken out as of 1 April.

How does the company form affect the YEL obligation?

The company form and your ownership share determine whether you need YEL insurance.

If you operate as a sole trader and work in your business, you need YEL insurance for yourself.

If your spouse works in the business, they must take out their own YEL insurance, regardless of whether they receive a salary.

If another family member works in your business without pay, they must also take out their own YEL insurance. If they are paid a salary, you must arrange TyEL insurance for them.

Read more about TyEL insurance

When do you need YEL insurance?

You need YEL insurance if:

  • you work in a managerial position in a limited company, and
  • you own more than 30 per cent of the shares or voting rights alone, or more than 50 per cent together with your family members.

If these conditions are not met but you work in the company and receive a salary, you need TyEL insurance.

When are you considered to be in a managerial position?

Examples of managerial positions include:

  • The Chief Executive Officer (CEO)
  • A Member of the Board of Directors
  • An administrative or business unit director
  • A person entitled to sign on behalf of the company by virtue of their position
  • A person who owns all the company’s shares or exercises equivalent actual control over the company
  • A person who works in the company and effectively directs its operations, even without a formal managerial title.

When do you need TyEL insurance?

You need TyEL insurance if you work in the company, receive a salary, and:

  • own no more than 30 per cent of the shares or voting rights alone, or no more than 50 per cent together with family members
  • are a shareholder who is not in a managerial position
  • are a family member of a shareholder but do not own shares in the company.

Read more about TyEL insurance

If you are a partner in a general partnership and work in the business, you need YEL insurance.

If a family member works in the partnership and receives a salary, they need TyEL insurance. If they do not receive a salary, they do not need either TyEL or YEL insurance.

Read more about TyEL insurance

If you are a general partner in a limited partnership and work in the business, you need YEL insurance.

If you are a silent partner, work in the business and receive a salary, you need TyEL insurance. If you are not paid a salary, you do not need either TyEL or YEL insurance.

If a family member who is not a partner works in the business and receives a salary, they need TyEL insurance. If they work without pay, they do not need either TyEL or YEL insurance.

Read more about TyEL insurance

When do you need YEL insurance?

You need YEL insurance if:

  • you work in a managerial position and exercise more than 30 per cent control alone, or more than 50 per cent together with family members
  • you are a shareholder working in the organisation and are personally liable for its obligations.

When do you need TyEL insurance?

You need TyEL insurance if you work in the organisation, receive a salary, and:

  • are a shareholder whose control is less than 30 per cent and who is not personally liable for the organisation’s obligations
  • are a family member of a shareholder.

Read more about TyEL insurance

If you are a light entrepreneur, meaning that you work for yourself and invoice your clients through an invoicing service, you need YEL insurance.

Under earnings-related pension legislation, a light entrepreneur is considered a self-employed person.

Read more about YEL insurance for light entrepreneurs

For the purposes of earnings-related pension legislation, the following are considered family members:

  • a spouse or registered partner, regardless of whether they live in the same household as the self-employed person
  • a cohabiting partner living in the same household as the self-employed person
  • a child, grandchild, parent, grandparent, adopted child or adoptive parent living in the same household as the self-employed person
  • a child, grandchild, parent, grandparent, adopted child or adoptive parent of a spouse who lives in the same household as the self-employed person and works in a managerial position.

Who is not considered a family member?

A child living in their own household is not regarded as a family member under earnings-related pension legislation.

Siblings, uncles and aunts are also not regarded as family members, even if they live in the same household as the self-employed person.

One YEL insurance policy covers all your entrepreneurial activities

If you work as a self-employed person in more than one business, you only need one YEL insurance policy. Set your YEL income so that it reflects the value of your work input across all your businesses combined.

Self-employment while receiving a pension

You can continue working as a self-employed person while receiving a pension, regardless of the type of pension you receive. Depending on your pension, YEL insurance may be either mandatory or voluntary. See the guidance below for different pension types.

If you are receiving an old-age pension, you may work as a self-employed person without YEL insurance.

If you wish, you can take out voluntary YEL insurance alongside your pension. Voluntary YEL insurance accrues additional pension at a rate of 1.5 per cent per year.

Take out voluntary YEL insurance online

Remember to claim the pension accrued during retirement no earlier than when you reach your highest retirement age.

See instructions on how to claim pension accrued during retirement

You need YEL insurance if you work as a self-employed person while receiving a partial old-age pension and your YEL income exceeds the minimum threshold for obligatory insurance, which is EUR 9,423.09 in 2026.

If your work input changes when you move to a partial old-age pension, apply for a change in your YEL income in Varma Online Service. You can find the application under YEL Insurance → Insurance policy information → Apply for a change in your YEL income.

Log in to Varma Online Service

How additional pension accrues

Self-employment carried out alongside a partial old-age pension accrues additional pension at a rate of 1.5 per cent per year. You can claim this accrued pension no earlier than at your lowest retirement age.

See instructions on how to claim pension accrued during retirement

You need YEL insurance if you work as a self-employed person while receiving a disability pension, partial disability pension, cash rehabilitation benefit or partial cash rehabilitation benefit, and your YEL income exceeds the minimum threshold for obligatory insurance, which is EUR 9,423.09 in 2026.

Note your earnings limit

Your YEL income may not exceed the earnings limit stated in your pension decision (your monthly earnings limit multiplied by twelve).

However, your YEL income may be up to EUR 990.90 per month, or EUR 11,890.80 per year (2026), even if your personal earnings limit is lower. This will not affect the payment of your pension.

You can check your personal earnings limit in your pension decision and in Varma Online Service.

Log in to Varma Online Service

How additional pension accrues

Self-employment carried out alongside a pension accrues additional pension at a rate of 1.5 per cent per year. You can claim this accrued pension no earlier than at your lowest retirement age.

See instructions on how to claim pension accrued during retirement

You need YEL insurance if you work as a self-employed person while receiving a years-of-service pension and your YEL income exceeds the minimum threshold for obligatory insurance, which is EUR 9,423.09 in 2026.

Note your earnings limit

Your YEL income may not exceed the earnings limit for a years-of-service pension (the monthly earnings limit multiplied by twelve). The earnings limit for a years-of-service pension is EUR 990.90 per month, or EUR 11,890.80 per year in 2026.

How additional pension accrues

Self-employment carried out alongside a pension accrues additional pension at a rate of 1.5 per cent per year. You can claim this accrued pension no earlier than at your lowest retirement age.

See instructions on how to claim pension accrued during retirement

Help with using our services

Take care of your YEL matters online

In our online service, you can, for instance

  • apply for a change in your YEL income
  • view your past and future YEL contribution
  • request an extended term of payment for an invoice

Sign in to the service using your personal banking codes.